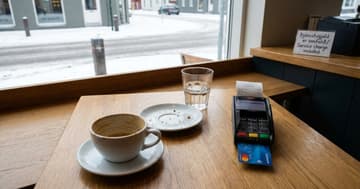
In early 2026, the global economy exists in a state of digital dominance, yet physical currency remains stubbornly present. A cashless society describes an economic system where financial transactions are conducted through digital information rather than physical banknotes or coins. While some futurists once predicted the total disappearance of cash by the mid-2020s, the reality is more complex. Digital payments offer speed, but they have also introduced questions regarding liberty.
Defining the digital-first economy
Modern cashless payments encompass everything from credit cards and mobile wallets to biometric scans and instant bank transfers. These systems rely on a robust digital infrastructure to verify and authorize transactions in real-time. For many consumers, the convenience of tapping a phone or watch has made the traditional leather wallet feel like a relic. However, this transition is not merely about speed; it represents a fundamental shift in value exchange.
Five years ago, many financial analysts predicted that cash would be obsolete by 2026. They pointed to the rapid adoption of contactless technology and the decline of physical bank branches. While the use of physical money has indeed dropped significantly, it has not vanished. The "end of cash" has proven to be an exaggeration, as the infrastructure required to support a 100% digital economy remains unevenly distributed across many different regions.
10 reasons why cash will never go away
Several critical factors ensure that physical currency remains vital. First, cash provides a safety net during power outages or cyberattacks. Second, it offers total anonymity for private transactions. Third, it is free to use, avoiding the processing fees that bite into small business margins. Fourth, physical money helps with tangible budget control. Fifth, it works without a battery or internet connection, making it the most resilient system available.
Sixth, cash is a legal tender that ensures universal acceptance. Seventh, it is an essential tool for teaching children about financial value. Eighth, it is immune to the types of digital fraud that target bank accounts. Ninth, it holds significant cultural and historical value in many societies. Finally, cash remains the only truly inclusive payment method that does not require a digital device or a formal banking relationship to participate in trade.
Privacy and the economically disadvantaged
One of the most significant dangers of a cashless society is the erosion of privacy. Every digital transaction leaves a data trail that can be tracked by banks and government agencies. This creates a permanent record of an individual’s movements and habits. Without the option of cash, every purchase becomes a piece of data that can be sold or used to restrict access to services, removing the historical wall between private life and institutional oversight.
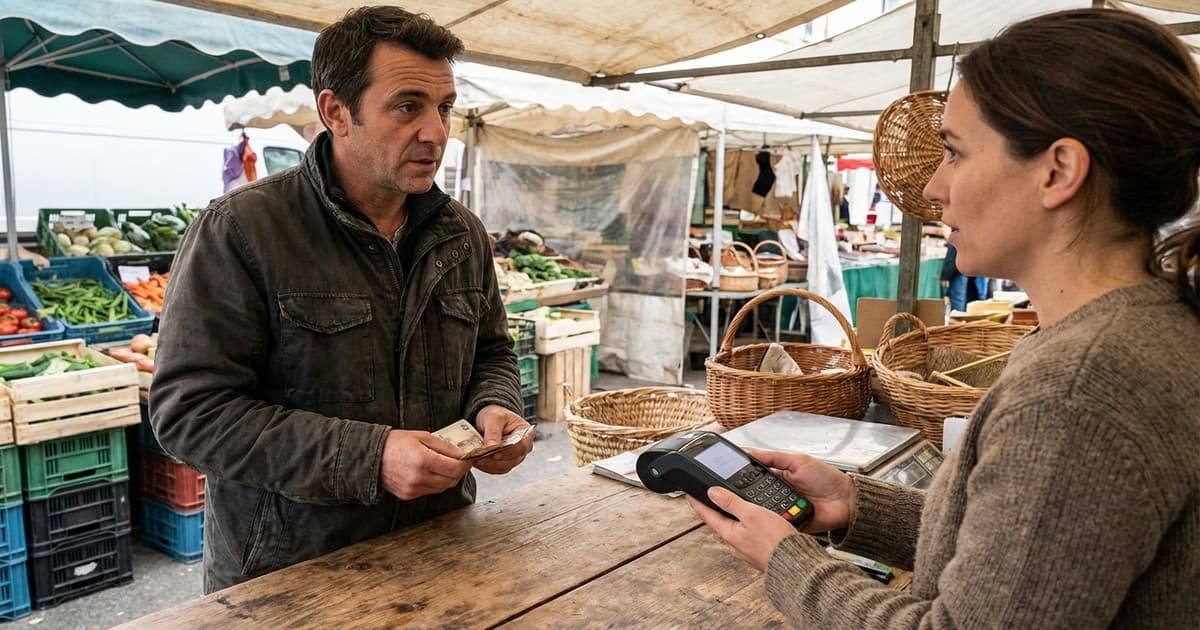
The move toward a digital-only economy also disproportionately affects the economically disadvantaged and the unbanked population. Millions of people lack the credit scores or stable addresses required to maintain a bank account. When businesses display "We are cashless" signs, they effectively lock out the most vulnerable members of society. This creates a tiered economy where participation in the marketplace is a privilege rather than a universal right.
The balance of modern commerce
As we navigate the complexities of 2026, it is clear that the future is not a choice between cash or digital, but a necessity for both. The push for a cashless society offers efficiency, but it must be balanced against the need for financial inclusion and personal privacy. While digital tools continue to evolve, the humble banknote remains an essential tool for freedom and social equity, ensuring that no citizen is left behind by the march of technology.